Uganda’s National Social Security Fund has been on an investment spree in recent years, but its decision to stay away from the Kenya Pipeline Company Initial Public Offer tells a lot. In recent years it has acquired significant stakes in large companies like MTN Uganda, Airtel Uganda and Kampala Mariott Hotel, while raising stakes in Kenya’s Safaricom, KCB Banks and other stocks across Uganda, Rwanda and Tanzania stock markets.
Its equity allocation has now expanded to 18.4 percent of its total portfolio (worth about 5.93 trillion shillings). The Fund says it is this strategic shift away from being heavilly reliant on government treasury bills and bonds that has driven its gains recently, allowing it to declare the record 22.53 percent interest rate to savers for the financial 2025/2026.
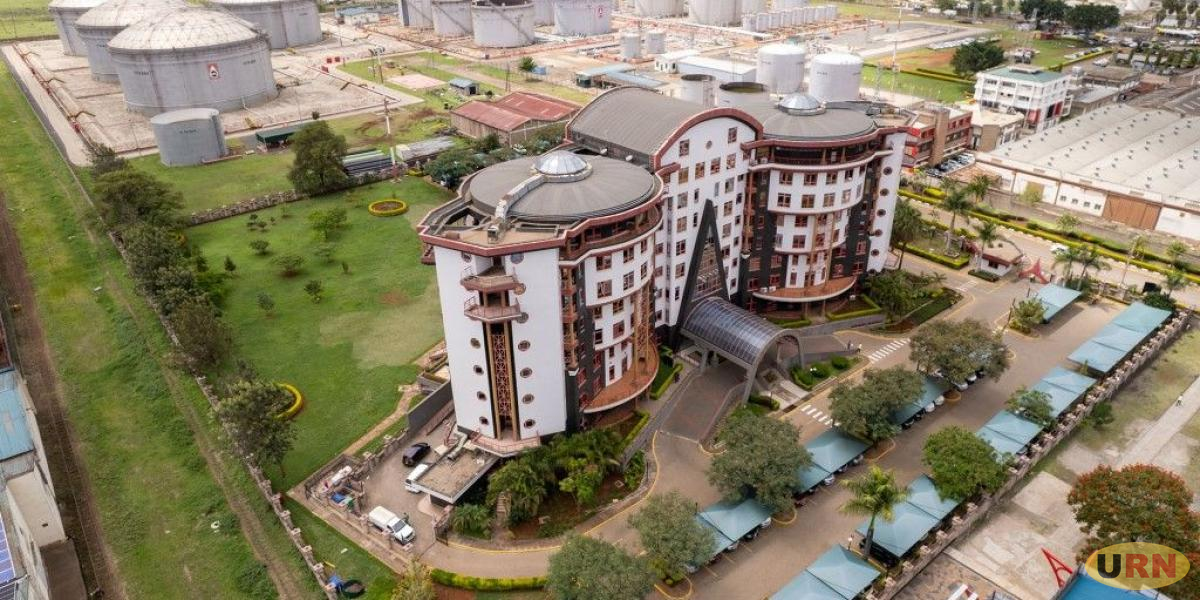
But the fund, Eastern Africa’s largest financial company by assets, stayed away from the recent floating of KPC, one of the region’s most valuable companies. NSSF Chief Investments Officer, Kenneth Owera says that NSSF makes long and comprehensive analyses of all investment offers presented to it before making a decision to invest.

NSSF, which recently came under pressure by Ugandan government officials to invest in infrastructure or development projects, says it did not see KPC as a viable opportunity due to its high pricing.
NSSF Deputy Managing Director, Gerald Kasaato, says that at 9 Kenya shillings (about 270 Uganda shillings) per share, they concluded that the stock was overpriced and would not guarantee the returns that the Fund seeks for its savers, under the current situation. He says the Price-to-Earnings (P/E) Ratio of KPC stock which is about 21, is too high.
The P/E ratio is the measurement that compares a company’s stock price to its earnings per share, showing how much investors are paying for each shilling of profit. In this case, investors would be paying 21 Kenya shilling for every 1 shillings of annual profit.
Kasaato says the highest P/E on a stock ever listed in East Africa was Safaricom, which NSSF also participated in, and adds that Safaricom presented attractive growth prospects, unlike KPC. Several analysts in Uganda and Kenya viewed the nine shillings per share as too high, saying the company had been highly overvalued. Investors then would be paying much for less.
Old Mutual Investment Group Uganda’s own evaluation put the company at about 141 shillings (4.61 Kenya shillings), which brings the total value of KPC to 2.38 trillion shillings (77.4 billion Kenya Shs), as opposed to KPC’s valuation of about 5 trillion shillings equivalent to 163.56 billion in Kenya Shillings.
“Based on our intrinsic valuation, using a combination of Discounted Cash Flow analysis and relative market comparables, we estimate a fair value of KSh 4.61 per share which implies a 49% downside to the IPO price of KSh 9.00,” says the financial and investment advisory firm. This means, Uganda and the other investors paid almost twice the amount they would have paid for what they got.
Old Mutual describes KPC positively in terms of profitability and dividend payouts, among others, especially due to its kind of business and unique position in East Africa, worth investing in, but says that investors should wait for a revision of the price.
“We anticipate a post-listing repricing as investor expectations normalize and improved trading liquidity enables clearer price discovery more closely aligned with intrinsic value.” A post-listing price correction usually happens when the stock failed to meet its targets on the market especially when investors do not go for it as had been expected.
The catch
Earlier analyses had already shown that KPC and the government of Kenya had overpriced the stock, which proved that response would be lower than targeted.
Uganda was not among those investors to apply for shares when the IPO was opened, and the trend was clearly telling a worryingly big undersubscription. Kenya then quickly yielded to Uganda’s demands including having a 20.15 percent share, having at least two members on the company’s board of directors and having veto powers on any pipeline tariff changes, business plans, dividend policy revisions and amendments to the company’s Memorandum or Articles of Association.
Uganda’s intervention meant that Kenya met and surpassed the targets with a 5.7 percent. The Ministry of Energy and Mineral Development says the profitability in relation to earnings is not the main issue, but having the ability to influence matters in a company that handles 95 percent of Uganda’s fuel supplies.
Permanent Secretary Irene Bateebe, who, along with Ministry of Finance Counterpart are now Non-Executive Board Members on the KPC Board, defended Uganda’s decision as a “deliberate strategic decision aimed at strengthening regional energy cooperation and safeguarding national interests.” Because Uganda contributes roughly two-thirds of KPC’s transit traffic revenue, she argues that holding a major stake ensures Uganda is no longer just a passive consumer but actively controls its own energy lifeline.
Ruth Nankabirwa, who oversaw the investment as then line minister, also defended the decision based on the concessions that Kenya had given Uganda. “Therefore, the decision to purchase shares is strategic, and the concessions outlined above provide assurances for the security of supply, accessibility, and affordability of petroleum products in Uganda,” she said.
As predicted, the trading of the KPC shares on the Nairobi Stock Exchange, over the first six months has been lukewarm, characterized by low liquidity and flat price movements since its public debut in March 2026. Market analyses show that because the stock was highly priced, it has struggled to sustain any major upward movement. The share prices remained at around 9 Kenya shillings for the initial months before briefly rising to 10 shillings around June.
However, it then fell to 8.7 shillings in august, before going back to 9. Market analyses however, show that the stock remains strong, far from crashing, because of the strong institutional support like Uganda National Oil Company’s 20.1 percent and Kenya Government’s 35 percent, which provide a strong base-URN. Give us feedback on this story through our email: kamwokyatimes@gmail.com