Bank of Uganda has discouraged the practice by savings groups of sharing surpluses, saying this denies them the ability to accumulate a capital pool for investments.
David Kalyango, Executive Director of Supervision and Regulation, says revenues should be retained as long as possible to not only ensure the growth of personal and group savings, but also contribute to the capital available for national development.
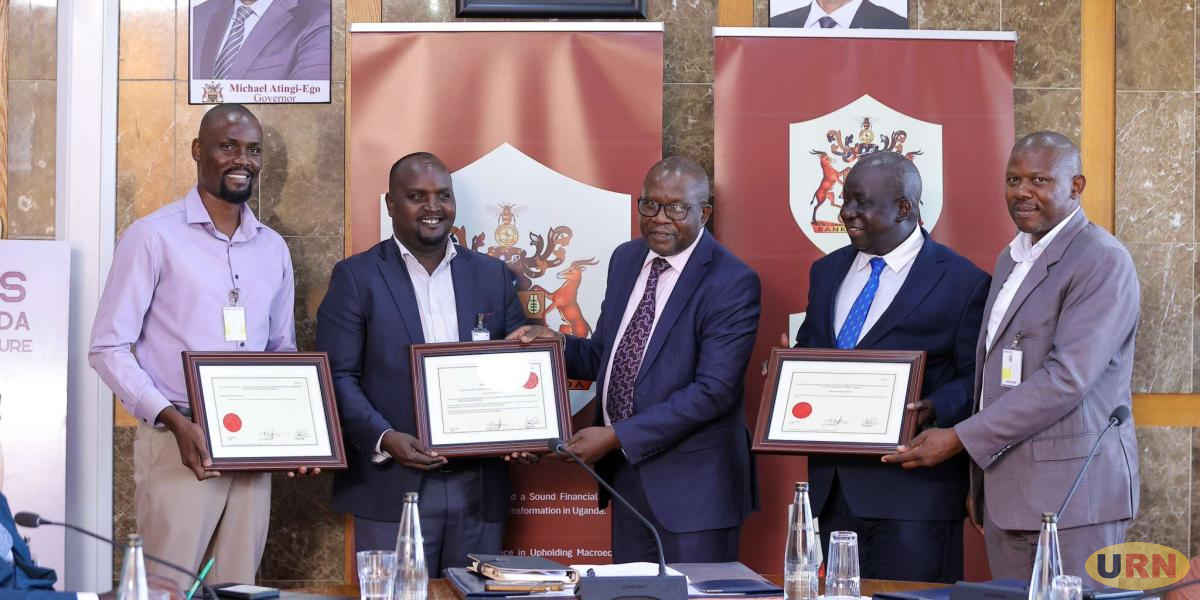
He handed over licences to four large Savings and Credit Cooperative (SACCOs) under the new regulations, which require eligible organisations to obtain a licence from the Central Bank.

“SACCOs are encouraged to retain surpluses rather than distribute them to enhance the pool of funds available to lend to the members at a lower interest rate. Money speaks only one language; ‘if you save me today, I will save you tomorrow,'” said David Kalyango.
He added that when prudently managed, SACCOs mobilise savings, provide responsible credit and support investment, help more Ugandans to participate in the money economy and contribute to achievement of the Government’s Tenfold Growth Strategy.
These licences also bring greater responsibility.
The newly licensed SACCOs are Uganda National Bureau of Standards Staff Cooperative Savings and Credit Society Limited, Kibaya Youth Development Cooperative Savings and Credit Society Limited (Mbarara), and CBS PEWOSA Nsindika Njake Eyeterekera Savings and Credit Cooperative Limited.
This brings the total number of compliant SACCOs to 10 so far, while another 35 applications have been submitted and are undergoing review.
BoU last week extended the deadline for submission of applications from September 30, 2026 to March 31, 2027, following consultations with the cooperative movement leadership and parliament, among others.
The mandatory licensing requirement targets SACCOs holding voluntary membership savings exceeding 1.5 billion shillings and institutional capital exceeding 500 million shillings.
BoU says there will be no further deadline extensions.
As the SACCOs grew bigger with savings in the billions of shillings, the government found it prudent to introduce another regulatory layer with the aim of giving protection to the public savings, as well as offer the public more trust in the industry.
“Effective licensing and proportional regulation help to build public trust and confidence in the SACCO sector. They give members greater assurance that their savings are in safe hands due to enhanced safeguards like Deposit Protection, and that they will be treated fairly,” Kalyango said.
Regulatory oversight also strengthens SACCO governance structures, accountability, risk management, financial reporting, and the institution’s internal control frameworks.
“As a result, SACCOs become more profitable and financially sound and resilient for the benefit of members and the communities in which they operate. Trust is the foundation of sustainable financial services, and it is built through competent leadership, sound controls, accurate records, ethical conduct and timely disclosures.”
Kalyango also urged Boards to provide effective oversight, and management to maintain adequate capital and liquidity buffers, while effectively managing credit risk. He added that management should always submit accurate returns to support regulatory oversight and protect members’ interests.
He reminded them that BoU-regulated SACCOs were eligible for subsidised funding through the Agricultural Credit Facility and Small Business Fund, to expand affordable financing for agriculture and business.
“Please take advantage of these opportunities. SACCOs are further encouraged to integrate sound environmental, social, and governance practices in their operations so that growth remains sustainable, responsible, and inclusive.”-URN. Give us feedback on this story through our email: kamwokyatimes@gmail.com